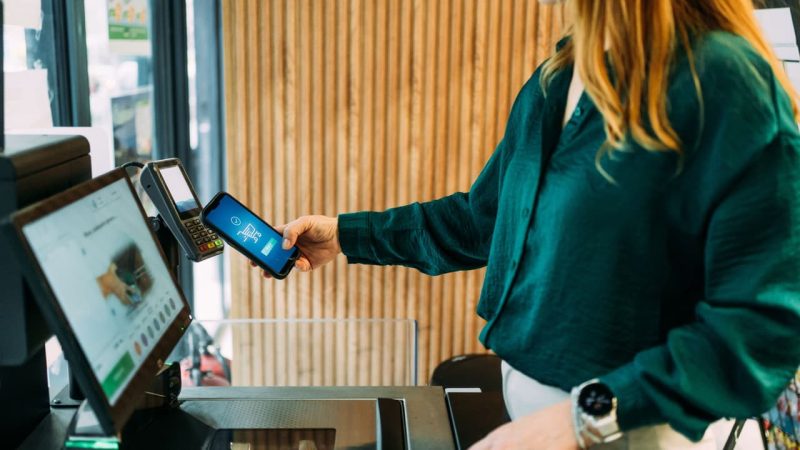
Australians facing rising inflation and interest rates are turning to retailer rewards programs in an effort to save money. But the appeal of a discount comes with a harder question: whether chasing points actually reduces household spending or simply encourages shoppers to put more through the checkout than they intended.
Rewards only help when the total falls
The attraction is straightforward. When everyday costs are climbing and borrowing becomes more expensive, any chance to trim a bill deserves attention. Retailer rewards programs can offer discounts or other incentives, but their value depends on the conditions attached and whether a purchase was necessary in the first place. Learn more on Investopedia.
A household that earns a reward while buying its usual groceries is in a different position from one that adds items solely to qualify for an offer. The reward may look attractive on its own. The additional spending still has to come out of the budget.
That distinction sits at the heart of the retail warning: discipline matters more than the size of a points balance. A saving is meaningful only if it leaves the shopper better off after the full transaction, rather than merely making an unplanned purchase feel justified.
For consumers, the useful comparison isn't simply between the advertised price and the member price. It's between the final cost of the shopping basket and what the same necessary purchases would cost elsewhere, including alternatives that don't come with points. Spending less remains the goal, even when the cheapest option offers nothing to collect at all on a membership account.
Spending thresholds can change the shopping decision
Offers tied to a minimum spend deserve particular scrutiny. If a shopper has to buy more than planned to unlock an incentive, the extra expense should be weighed against the reward's usable value. The arithmetic can be less flattering than the promotion, especially when the added items aren't needed or won't be used before they spoil.
Timing also matters. Bringing forward an essential purchase may be manageable for one household but leave another short of money for a bill. A discount doesn't remove that pressure. Nor does a future reward necessarily help with an expense that needs to be paid now.
Shoppers can protect themselves by setting a list and a spending limit before opening an offer or entering a store. Checking the price per unit can help distinguish an actual bargain from packaging that merely looks economical. And comparing products without factoring in points first makes the underlying price easier to judge.
None of this means shoppers must avoid loyalty schemes. It means the scheme should follow the budget, not set it. Walking away from an offer can be the better financial decision when meeting its terms requires buying something that wasn't otherwise going into the basket that day.
Check redemption rules before counting the savings
Rewards aren't always the same as cash. Depending on the program, their usefulness can turn on redemption rules, eligibility requirements or expiry conditions. Reading those terms helps establish whether an advertised incentive can actually be used for something the household needs, at a time when it needs it.
Membership can also involve sharing information about purchases. Consumers should check what information a retailer collects, how it may be used and which communications they can decline. Personalised offers may be convenient, but convenience isn't proof that a promoted product is the cheapest suitable choice.
A practical review is to look at money spent alongside rewards redeemed, rather than treating accumulated points as savings already achieved. Unused incentives don't lower the grocery bill. Neither does a purchase that costs more overall because a shopper stayed loyal instead of comparing prices.
The growing appeal of retailer rewards programs reflects the pressure on Australian budgets as inflation and interest rates rise. Yet participation alone says little about the financial outcome. For each household, the test is personal and concrete: whether membership supports purchases it would make anyway, reduces the amount paid and leaves enough money for obligations that no points offer can pay directly.
As Australians weigh their next shopping trip, the safest measure of success remains money kept, not points collected. Future offers should earn their place in the household budget first.
Originally reported by News. View original.